Product Analytics · Options

Five pricing models, one workbench.

A rebuilt options analytics dashboard: multi-leg strategy construction with American exercise, five pricing models side by side, a Greeks lab, and exotics.

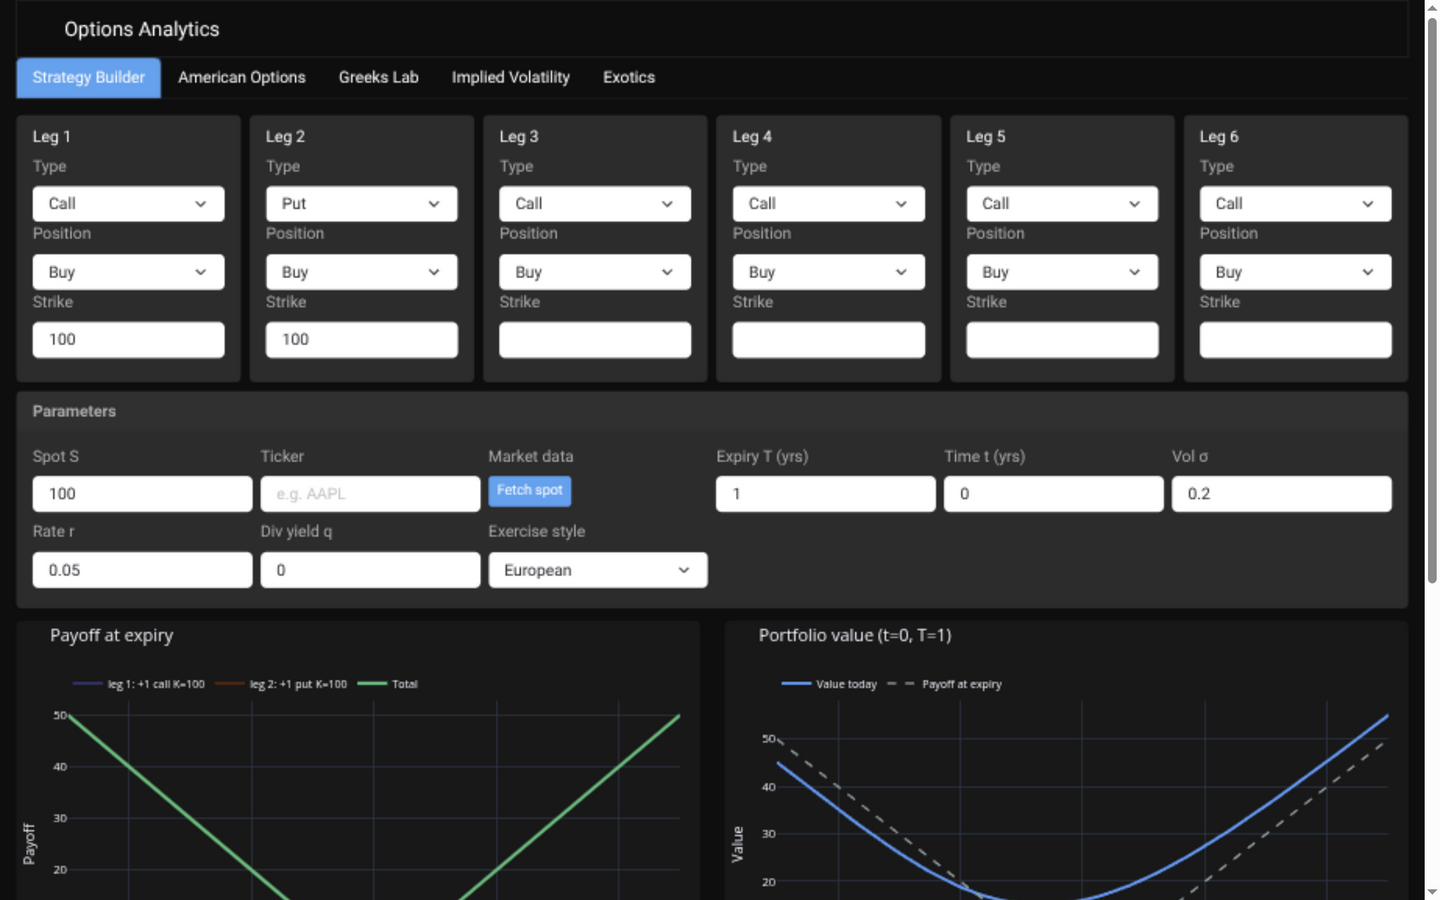
Six-leg options strategy builder in the Options Analytics dashboard with live pricing
Strategy Builder: legs table with strikes and quantities, live payoff and pricing underneath.
Greeks lab in the Options Analytics dashboard showing sensitivity charts
Greeks Lab: sensitivity surfaces across spot, time, and volatility for the structured position.

Five modules share one pricing core.

Every module draws on one pricing library, so the price in the builder matches the price in the Greeks lab.

ModuleWhat it does
Strategy BuilderUp to 6 legs of calls, puts, and stock (buy or sell, European or American) with payoff and current-value overlays plus portfolio Greeks.
American OptionsFive pricing models side by side with early-exercise premiums vs. Black–Scholes, runtimes, and convergence charts.
Greeks LabTwo instruments on one chart: Δ, Γ, ν, Θ, ρ against spot, time, vol, and rates, plus N(d1)/N(d2) moneyness.
Implied VolatilityEuropean (Brent root-find) and American (trinomial) IV with back-solve verification and a live-quote workflow.
ExoticsAsian, barrier, and lookback via seeded Monte Carlo with standard errors; digital options in closed form.

Trading conventions baked in

  • Theta per day; vega and rho per 1% move, displayed the way traders quote them.
  • Ticker → expiry → strike → bid/ask/mid auto-fill for real-quote IV work.
  • Dividend yield support and Yahoo Finance spot fetching keep the builder honest on real names.

From pricing library to product

The numerical methods research became the backbone of the product.

  • comp_methods (trees, finite differences, LSM Monte Carlo, Greeks, and rate models) is vendored from the American_Options project.